Facebook Marketplace Safety: How to Buy and Sell Without Getting Scammed
The most common Facebook Marketplace scams and how to avoid them: fake payments, verification-code tricks, overpayment, shipping scams and safe meetups.
How buy now, pay later works, its risks (late fees, overspending, credit reports, weaker dispute rights), the rules in the US and UK, and safer ways to use it.
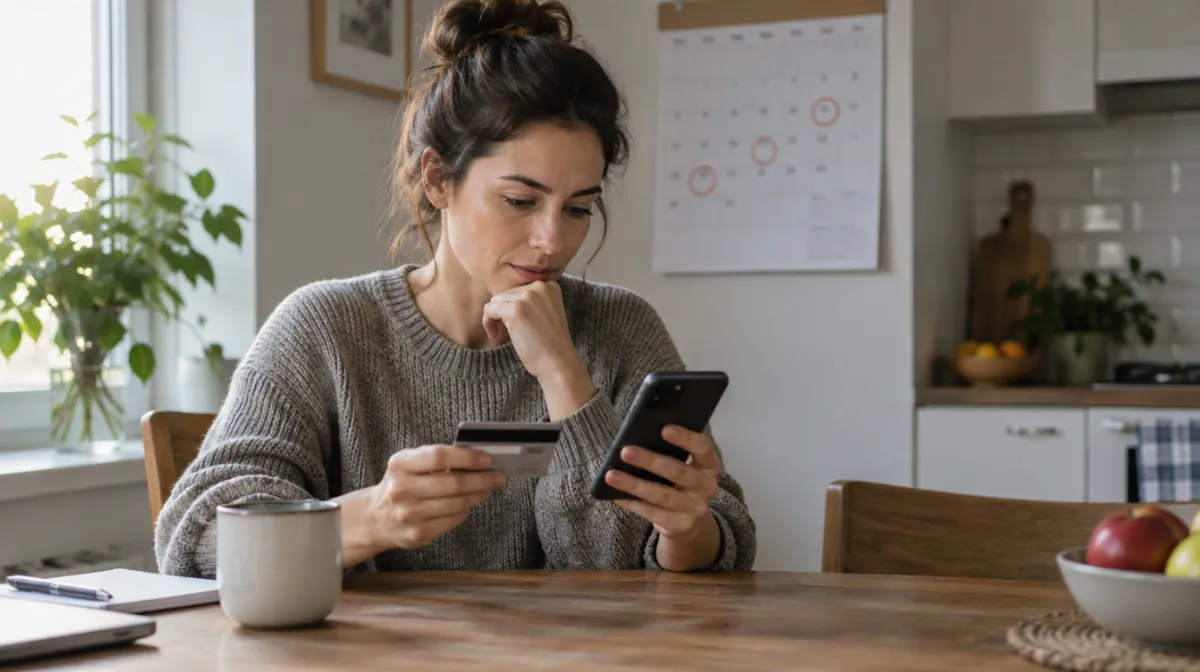
Buy now, pay later (BNPL) lets you split a purchase into smaller payments. The most common version is “pay in 4”: 25% at checkout, then three more payments every two weeks, usually with no interest if you pay on time. It’s convenient, but the risks are easy to underestimate: late fees, several plans running at once, spending more than you planned, messy returns and, increasingly, effects on your credit record. Here’s how it works, what the rules are and how to use it without getting caught out.
| Type | How it works | Typical cost |
|---|---|---|
| Pay in 4 | Four equal payments over about six weeks | Usually interest-free; late fees may apply |
| Pay in 30 | Pay the full amount within 30 days | Usually interest-free if paid on time |
| Monthly instalments | Longer loans over months or years | Often charges interest, sometimes at a high APR |
That last point is exactly why it needs care. Splitting a price makes it feel smaller than it is.
Miss a payment and many lenders charge a late fee. If automatic payments fail because your bank account is short, your bank may charge you too.
It’s easy to have several plans with different lenders and due dates. Each looks small; together they can strain a monthly budget.
Policymakers have raised concerns that BNPL may encourage people to spend more than they otherwise would. A basket that’s “only $25 today” can be $100 you didn’t plan to spend.
If you return an item, the refund has to travel from the retailer to the lender before your plan is adjusted. In the meantime, you may still be expected to keep paying. When the Consumer Financial Protection Bureau studied the market, it found that more than 13% of BNPL transactions in 2021 involved a return or dispute.
Some lenders report BNPL loans to credit bureaus, and newer scoring models can use that data. Missed payments can hurt your credit, while on-time payments may not always help if the lender doesn’t report them. Unpaid balances can also be sent to collections.
Monthly plans for bigger purchases can carry interest. Compare the APR with other options before agreeing.
In May 2024, the Consumer Financial Protection Bureau issued an interpretive rule that treated pay-in-4 lenders like credit card providers for certain purposes, including the right to dispute charges and get refunds for returns. That rule was withdrawn in May 2025, and the Bureau said it didn’t intend to reissue it. In practice, your protections depend mainly on the lender’s own policies, general consumer protection law and any state rules, so read the terms before you agree.
Since 15 July 2026, most interest-free BNPL (called Deferred Payment Credit) offered by third-party lenders has been regulated by the Financial Conduct Authority. Lenders must be authorised or in a temporary permissions regime, check that you can afford the repayments, give clear information and support customers in difficulty, and you can take unresolved complaints to the Financial Ombudsman Service. Plans offered directly by a retailer, rather than through a separate lender, aren’t covered by the new rules.
| Option | Cost if managed well | Dispute protections | Credit impact |
|---|---|---|---|
| Pay in 4 | Free | Depends on lender and location | May be reported |
| Credit card | Free if paid in full monthly | Strong legal protections in many countries | Reported; builds history |
| Saving up | Free | Depends on how you pay | None |
Our guide to buyer protection with PayPal, cards and banks explains how payment methods compare when something goes wrong, and returns and refunds rights covers what retailers must offer.
Fake stores increasingly advertise “pay later” at checkout to look legitimate. Check any unfamiliar shop before you buy; our guide to online shopping scams shows the warning signs.
Contact the lender before you miss a payment and ask about hardship options. In the US, nonprofit credit counseling agencies offer free or low-cost help. In the UK, MoneyHelper provides free, impartial debt advice.
It can. Some lenders report loans to credit bureaus, and missed payments can harm your credit. Check each lender’s reporting policy.
Yes, under the retailer’s return policy, but the refund must reach the lender before your plan is updated. Tell the lender about the return and keep making required payments until it’s confirmed.
It depends where you live. In the UK, most third-party BNPL has been FCA-regulated since 15 July 2026. In the US, there’s no BNPL-specific federal rule after the 2024 interpretive rule was withdrawn, although general consumer laws and some state rules apply.
Every article is edited by a human and checked against our editorial policy. Spotted a mistake? Tell us.
The most common Facebook Marketplace scams and how to avoid them: fake payments, verification-code tricks, overpayment, shipping scams and safe meetups.
Ten warning signs of a fake online seller: prices too good to be true, new accounts, stolen photos, off-platform payments and pressure tactics, plus what to do.
Which online payment methods protect buyers: PayPal Goods and Services, credit and debit cards, chargebacks, payment apps and bank transfers, and what to avoid.